← back317matt.com· demo · kalshi
live[email protected]
← all builds
§ 01 · quant · forecasting · automated trading

An algorithmic trading desk built on a weather model.

Two automated strategies on Kalshi's event markets. The flagship turns a skill-weighted, multi-model weather ensemble into market-implied probabilities and trades only the edges that survive a closing-line-value test. It's probabilistic forecasting, expected value, calibration, and risk — the same toolkit behind financial modeling and valuation.

● Walkthrough only — fabricated market data. P&L is redacted throughout; this shows the method, not the book.

Part 1From weather model to trade

A multi-model weather ensemble forecasts tomorrow's NYC high as a distribution, gets mapped onto Kalshi's temperature brackets, and where the model disagrees with the market the desk places an RSA-signed order — then alerts Telegram.

Part 2The system & the discipline

Two strategies running 24/7 as services — the weather edge and an expiration-premium collector — with closing-line-value tracking and Brier calibration before any edge is believed. P&L stays private; the method is the point.
§ 02 · the screens
Multi-model ensemble
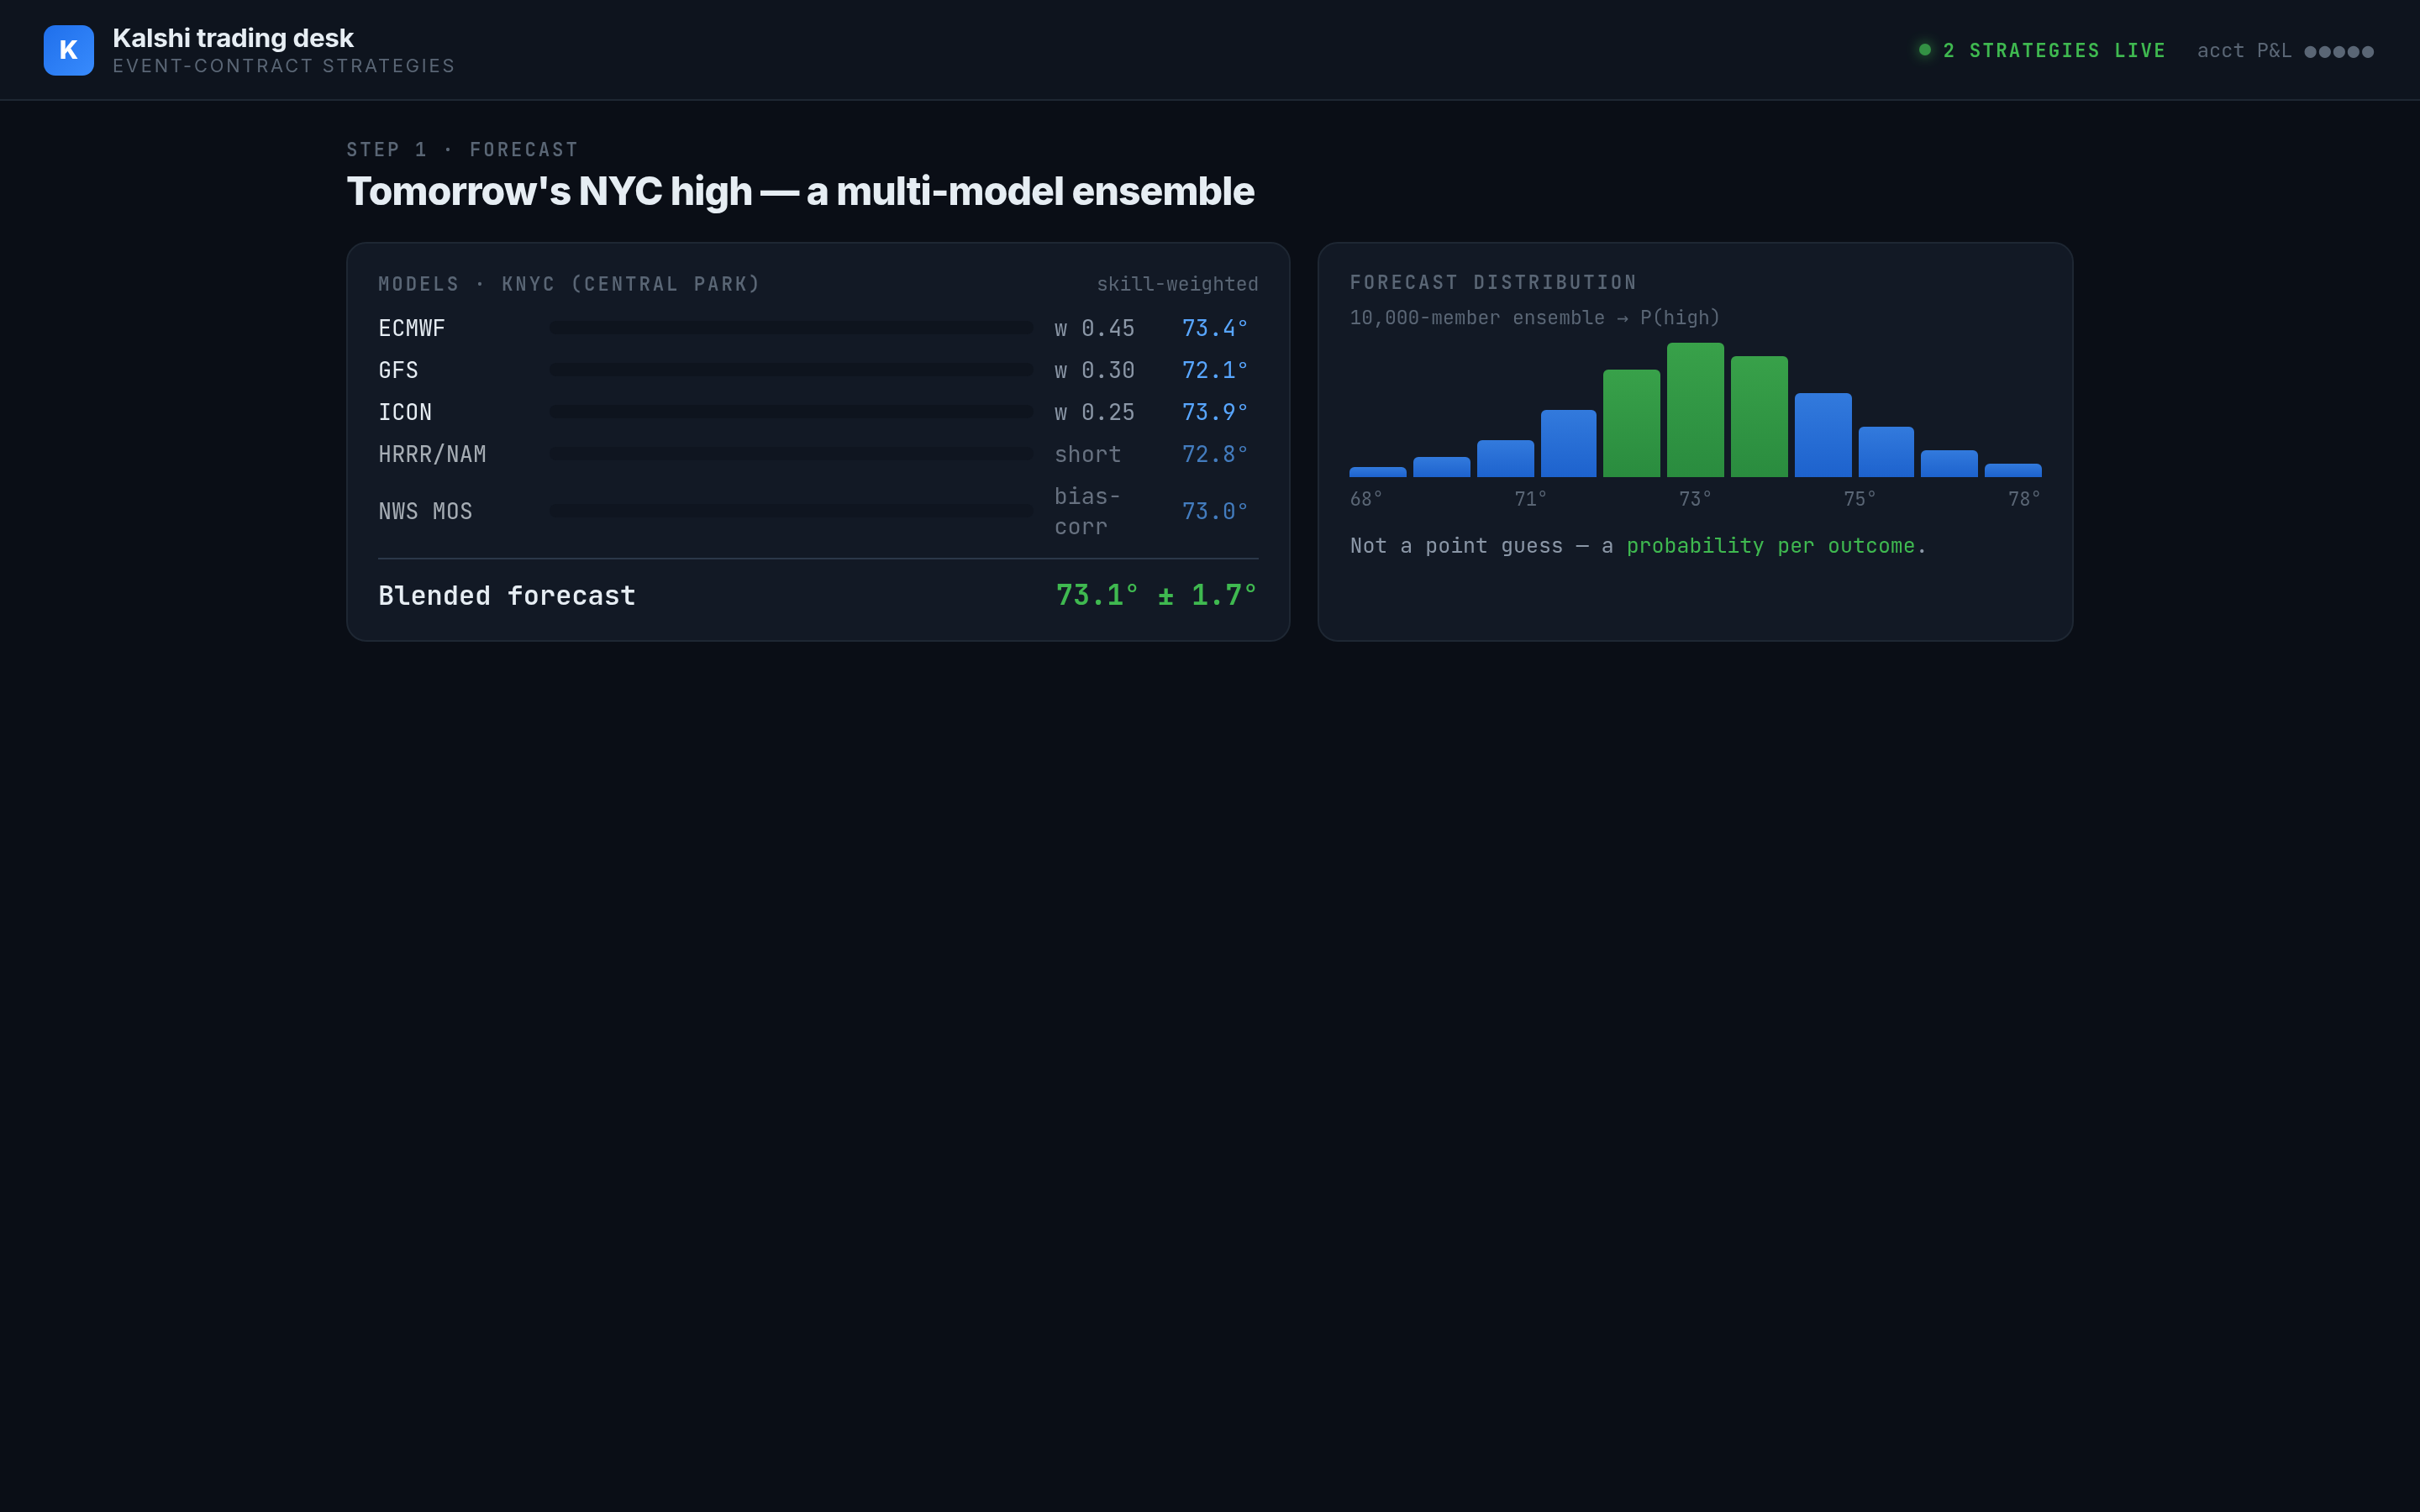
Multi-model ensembleGFS, ECMWF, and ICON blended by skill weight (plus HRRR/NAM short-range and NWS MOS bias correction) into a probability distribution for tomorrow's NYC high — not a point guess.
Model vs market
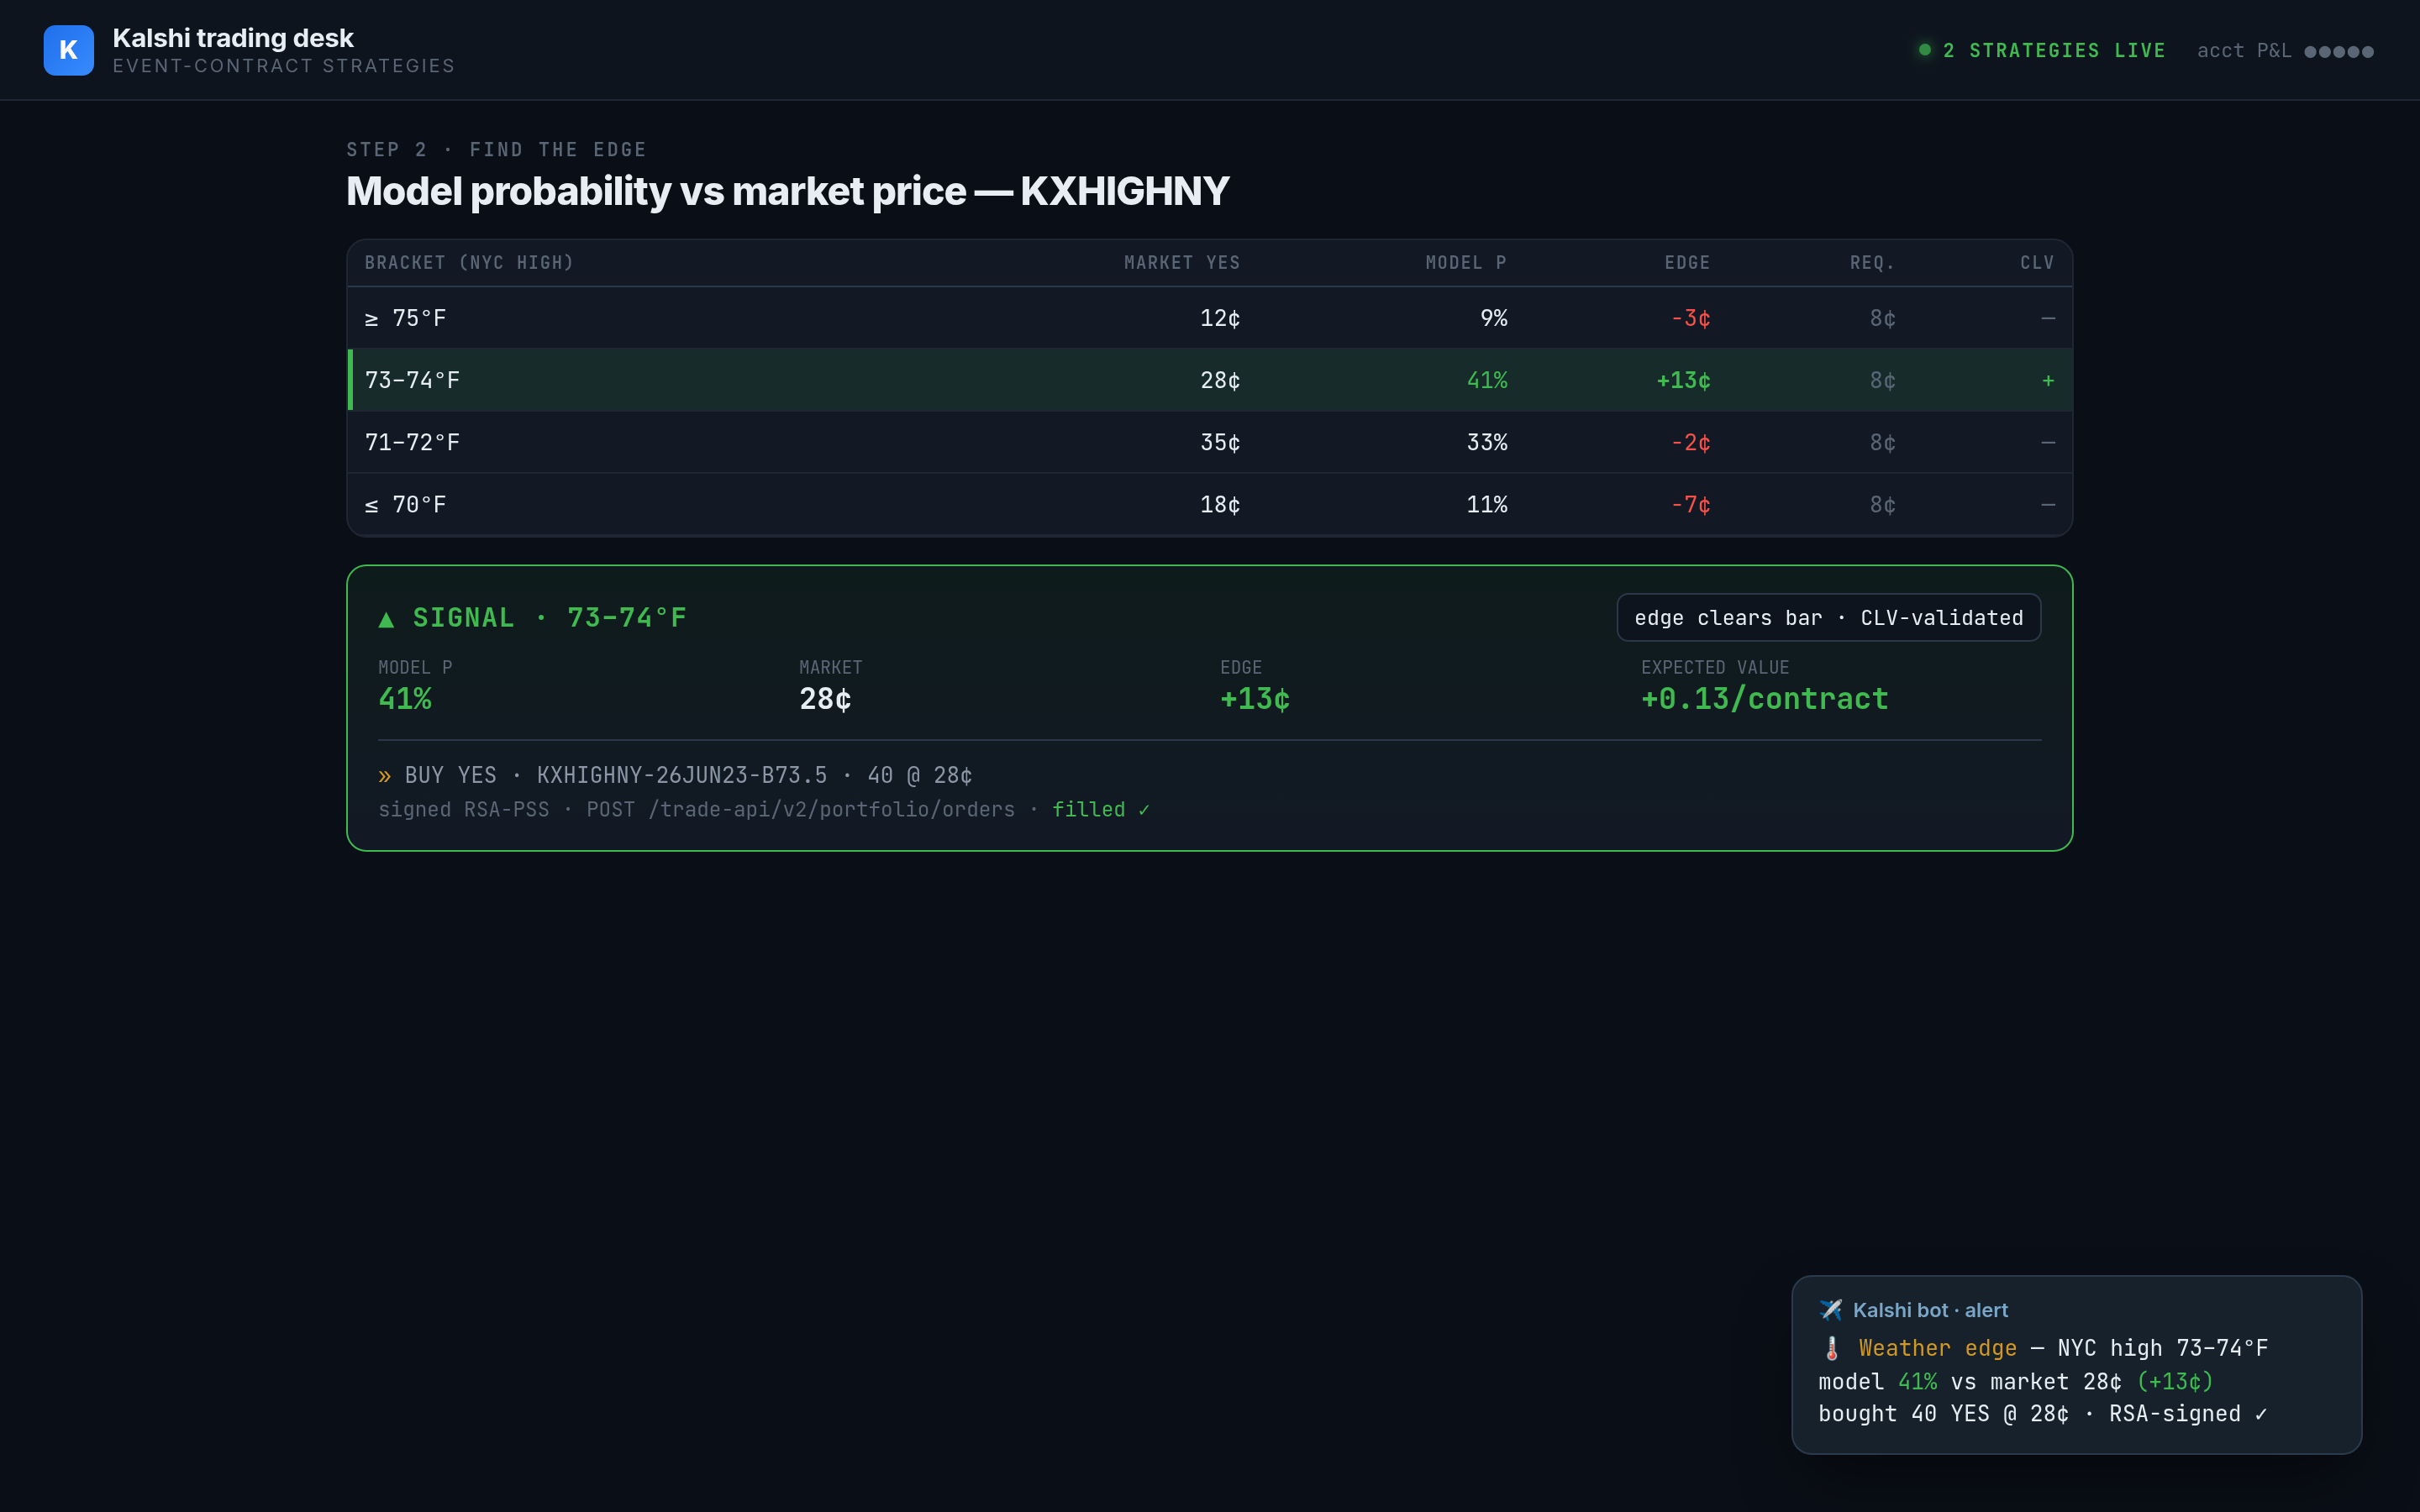
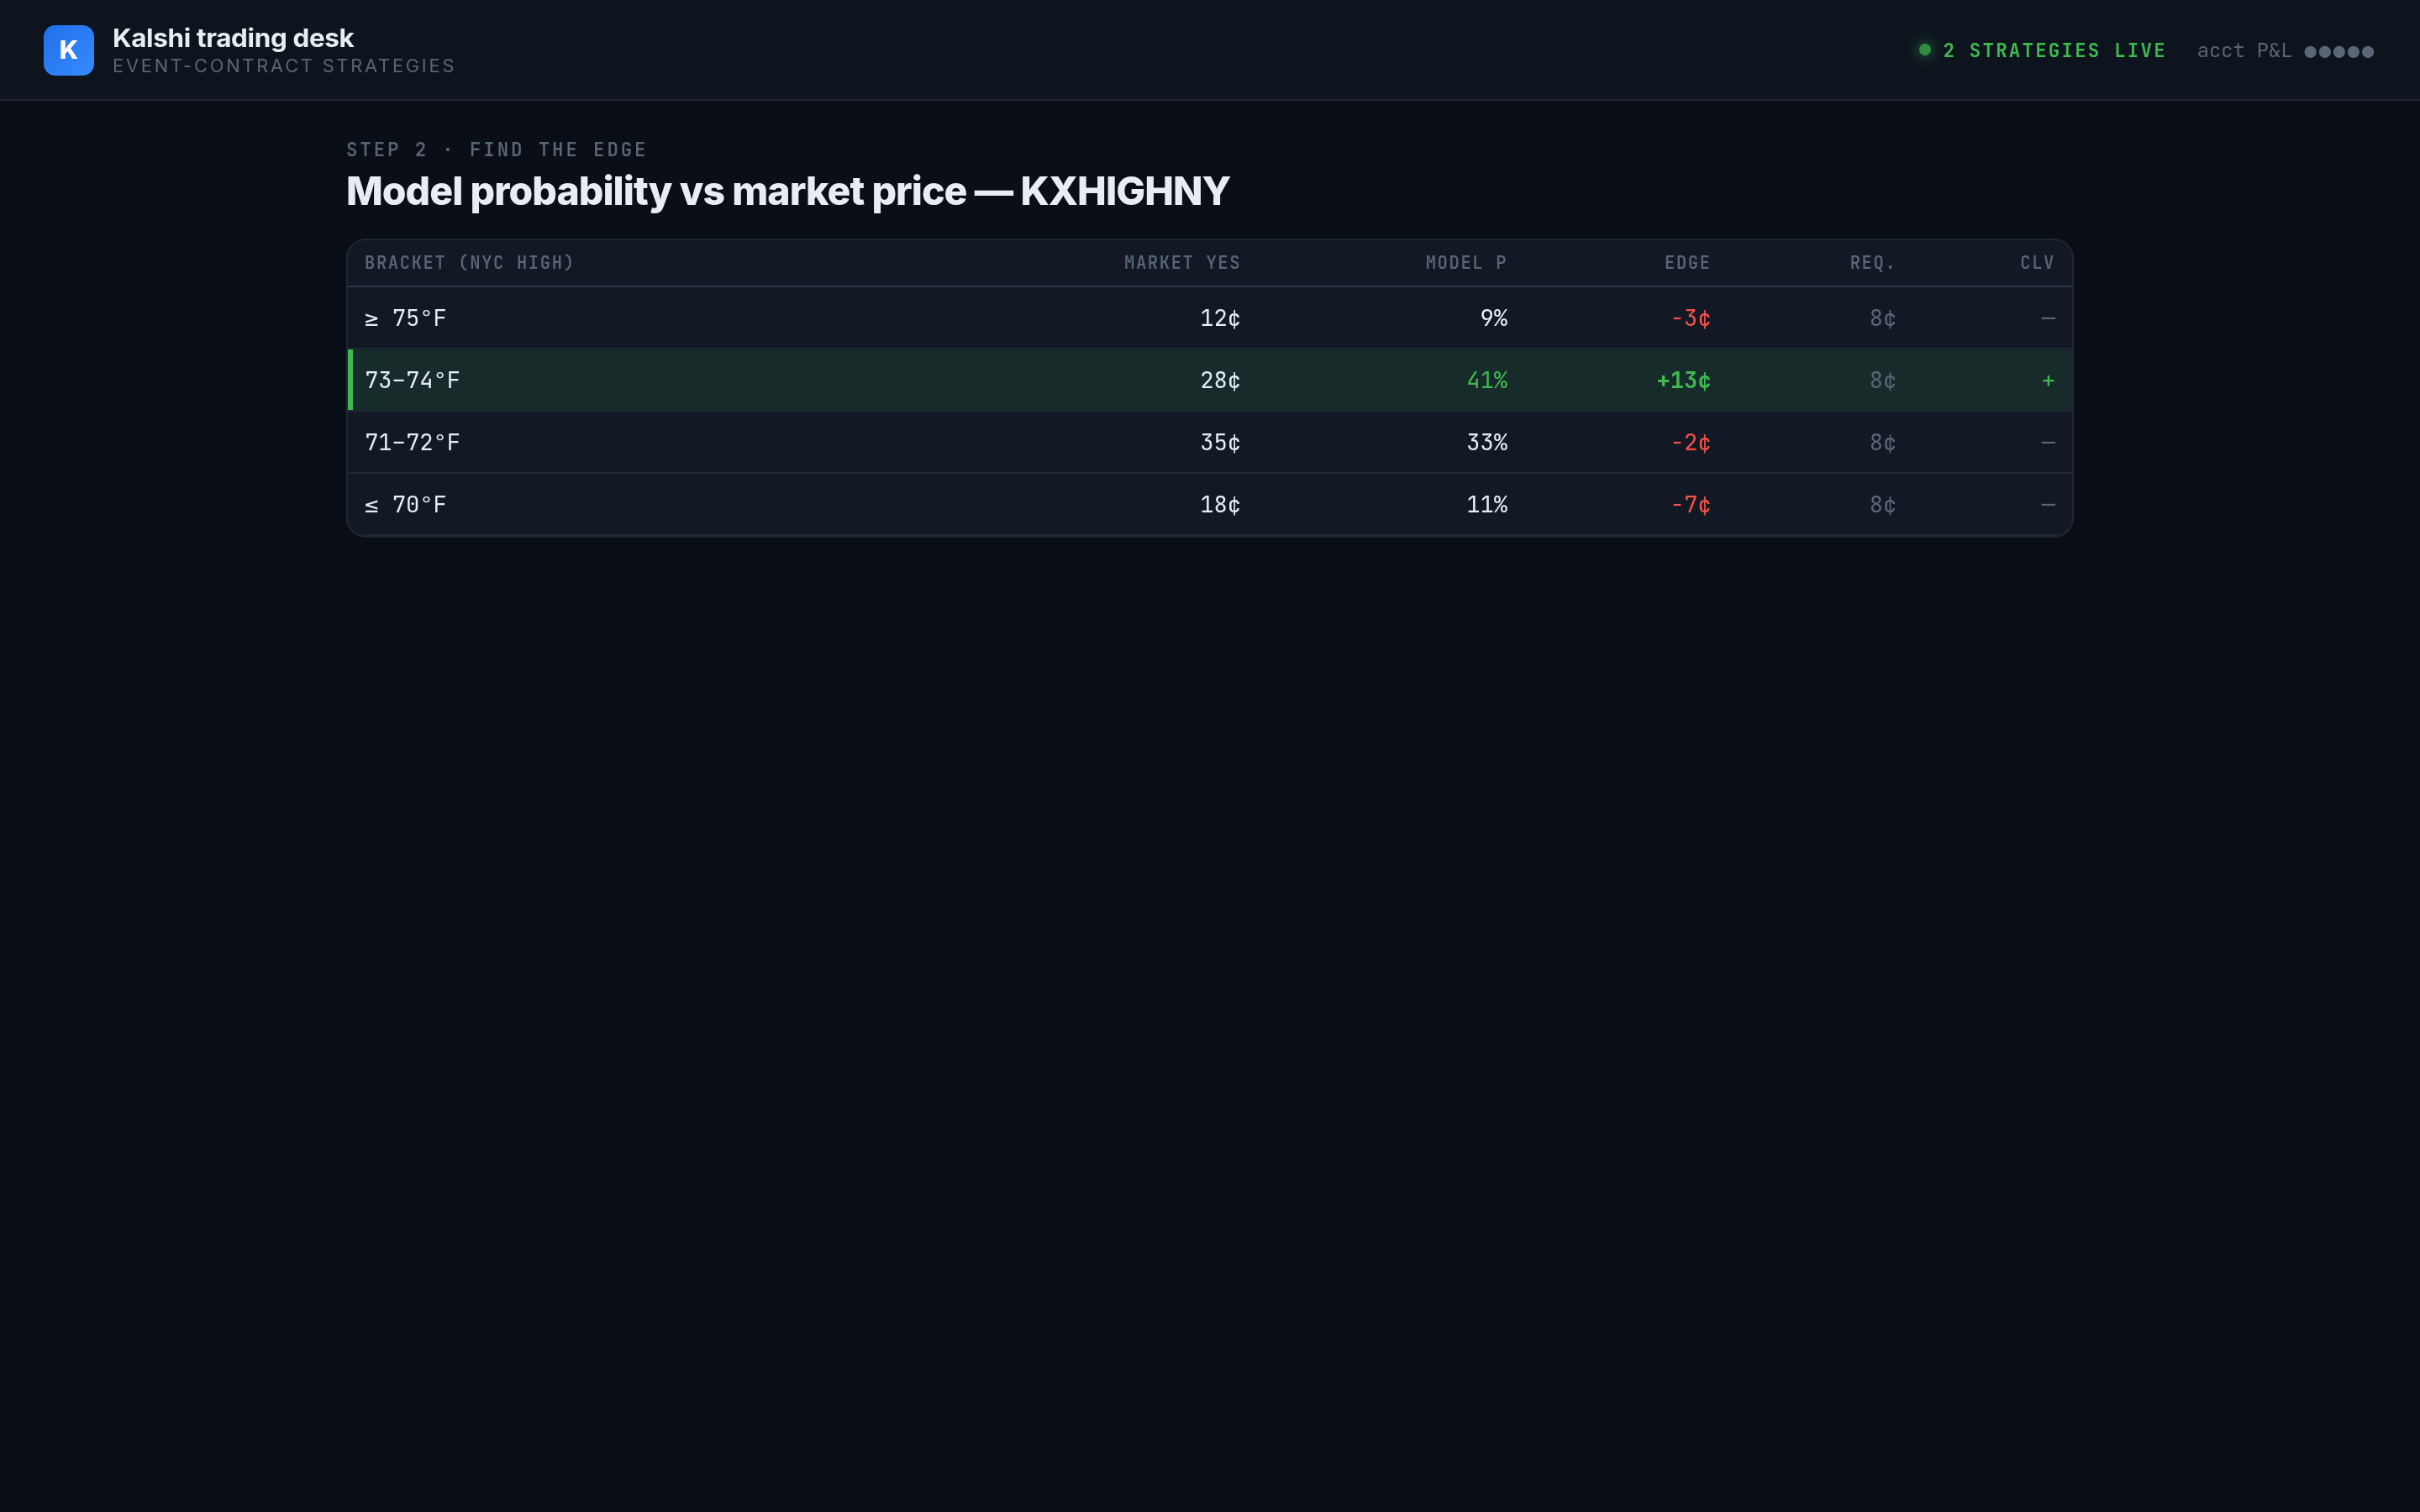
Model vs marketThe forecast distribution is mapped onto Kalshi's NYC high-temperature brackets (KXHIGHNY); model probability is compared to the market's YES price to surface mispricing.
Edge → signal → order
Edge → signal → orderA 73–74°F bracket priced at 28¢ that the model puts at 41% is a +13¢ edge. It only trades after the edge clears a required threshold and closing-line value validates it — then an RSA-PSS-signed order goes to Kalshi.
The desk (P&L redacted)
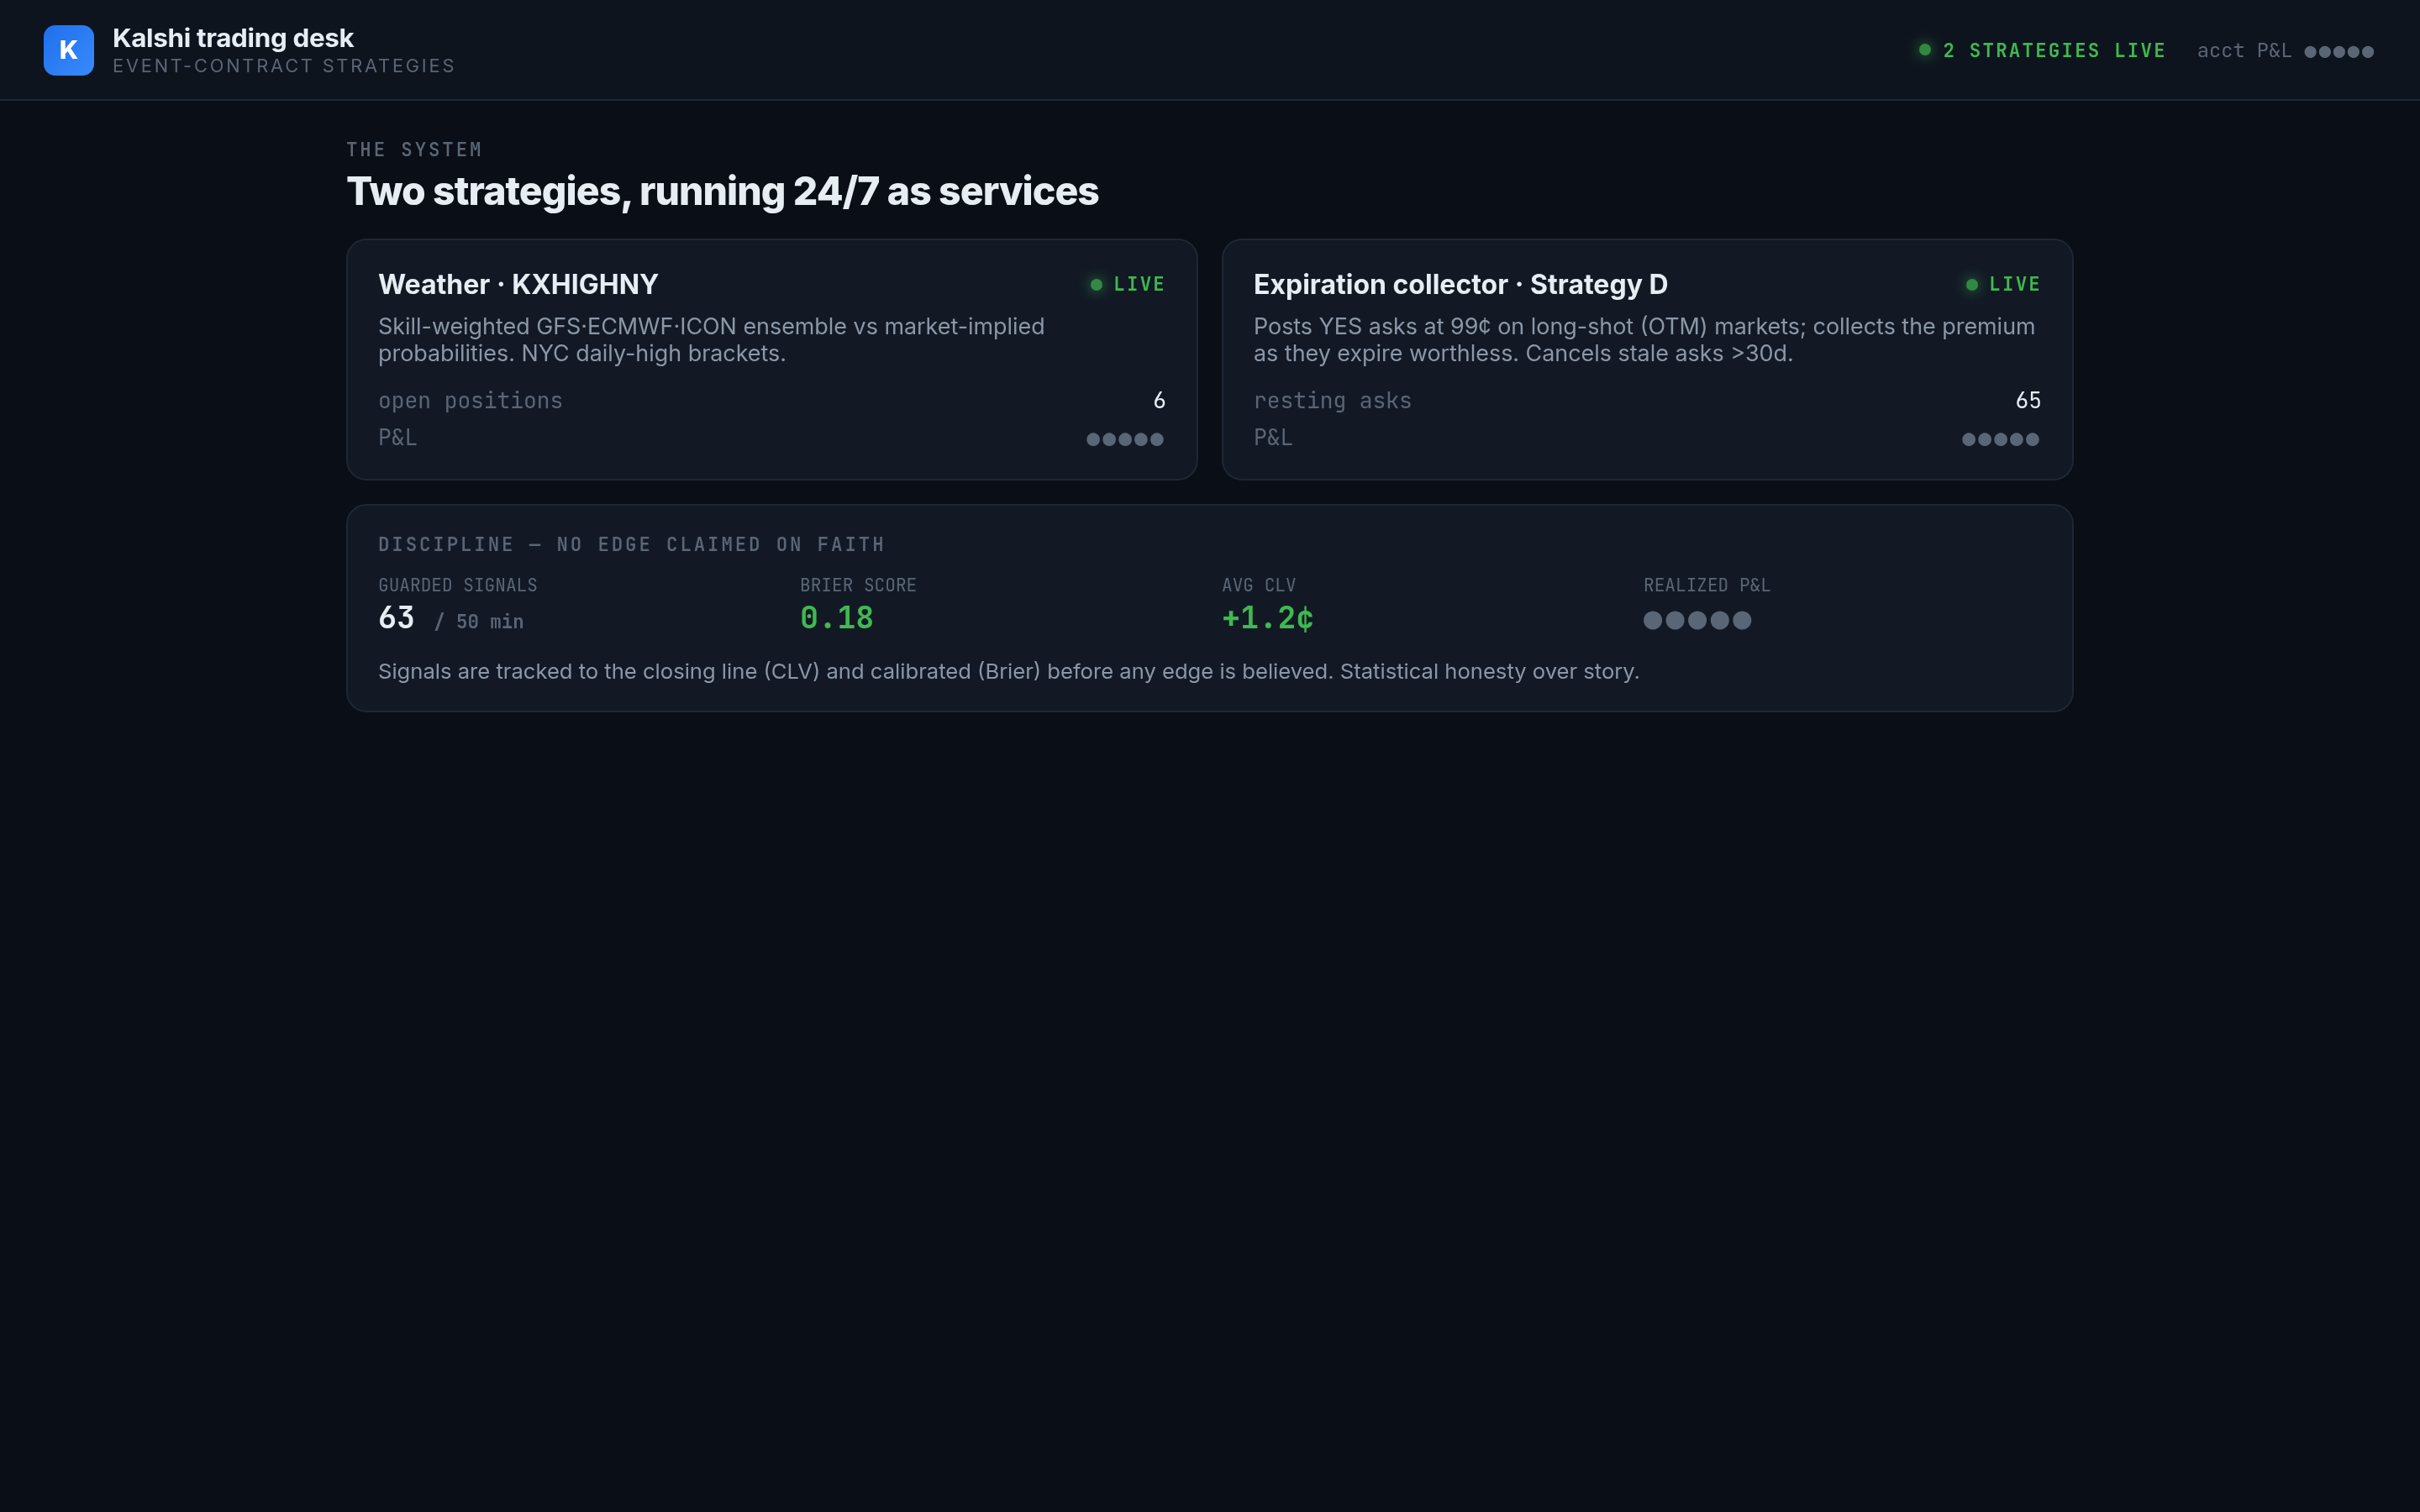
The desk (P&L redacted)Two live strategies — the weather model and Strategy D, which posts YES asks at 99¢ on long-shot markets to collect premium. Discipline: 50+ guarded signals, Brier calibration, CLV tracking before any edge is claimed.
The stack
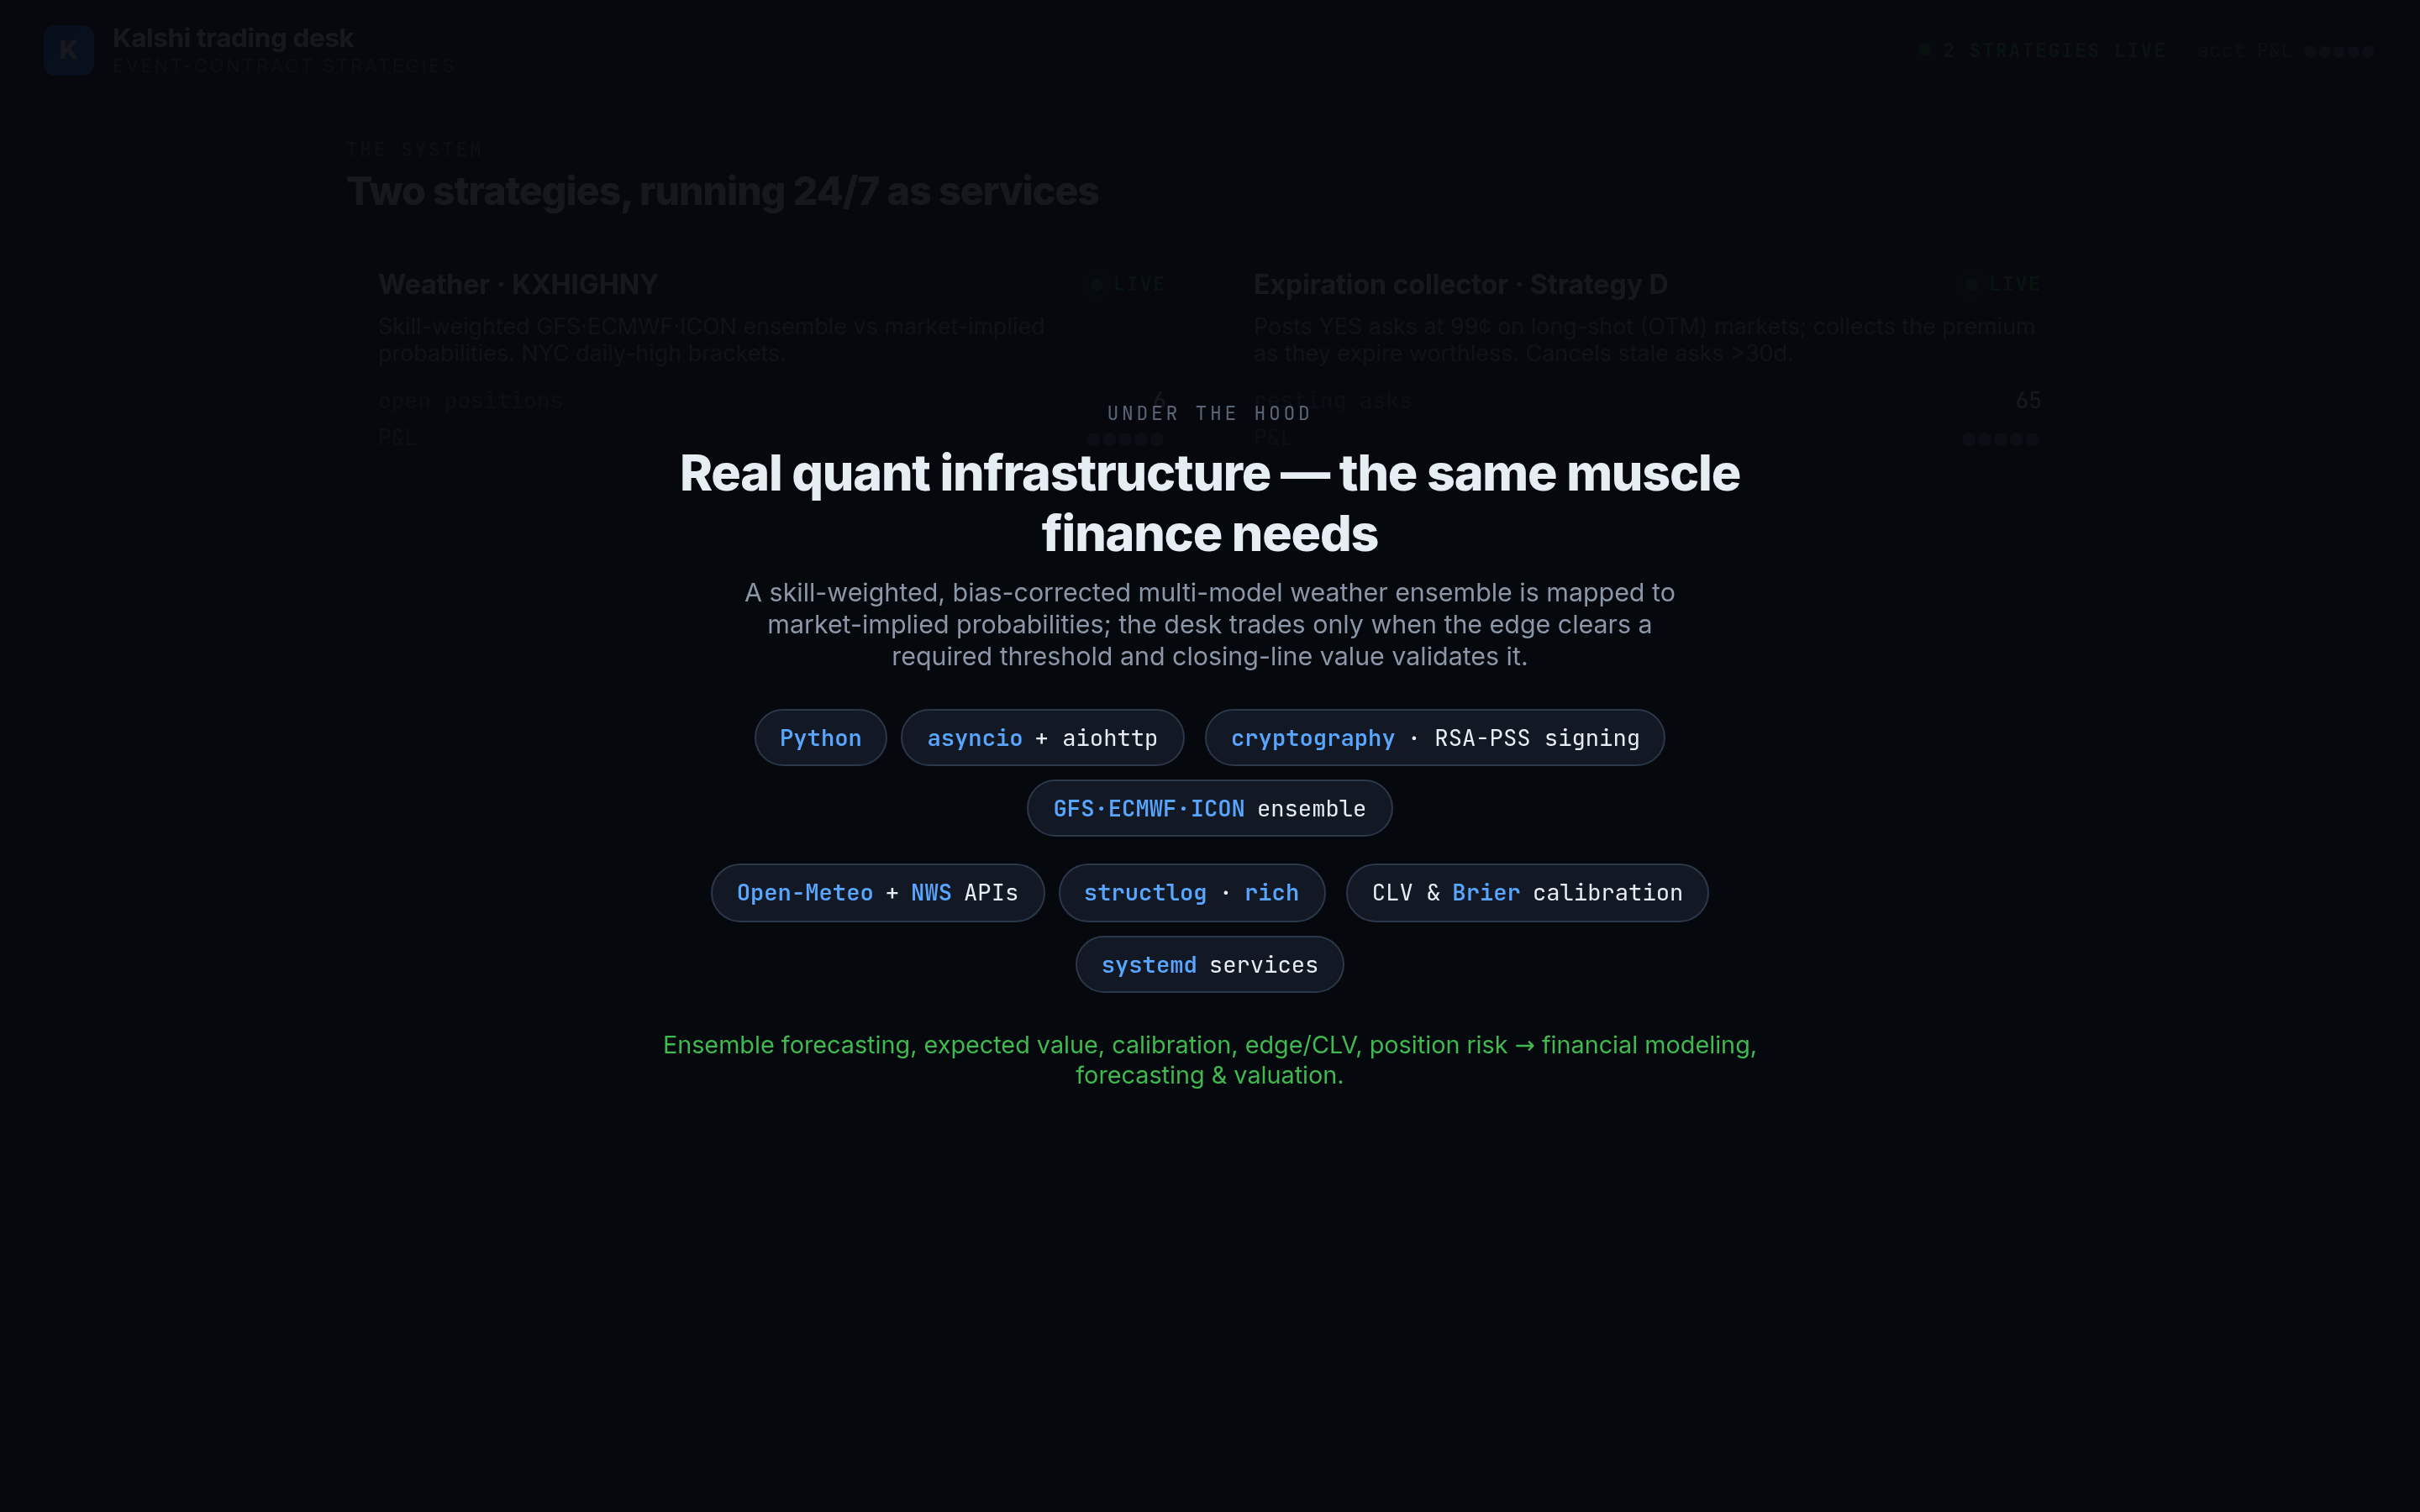
The stackPython · asyncio + aiohttp · cryptography (RSA-PSS request signing) · Open-Meteo + NWS ensemble APIs · structlog · rich · systemd services. Ensemble forecasting, expected value, calibration, and risk map straight onto financial modeling and valuation.